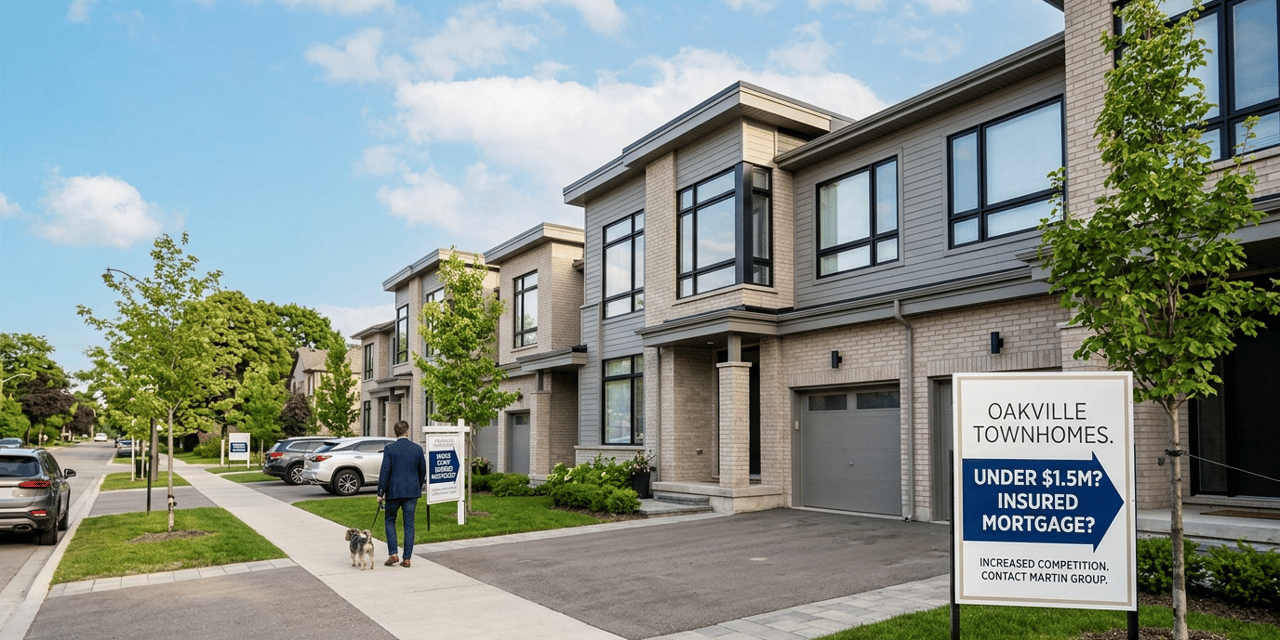
The Direct Answer: A Competitive Shift for Oakville Townhomes
The expansion of the insured mortgage cap to $1.5 million has effectively removed the "20% down payment barrier" for Oakville’s primary townhome inventory. Previously, properties over $1M required a minimum of $200,000 upfront. Now, qualified first-time buyers and purchasers of new builds can enter the market with significantly less capital—roughly $125,000 for a $1.5M property. This change has intensified competition, particularly for freehold townhomes, as more families can now compete for high-quality assets in top-tier school catchments.
Note: The market figures in this post reflect data available in March 2026. Prices change month to month — for the latest numbers, see the newest market update on our blog.
The Deep Dive: Unlocking the "Missing Middle"
The federal policy shift introduced in late 2024 has fundamentally altered the math for Oakville real estate. By raising the insured limit from $1M to $1.5M, a vast segment of the market: young professionals and "Sandwich Generation" families who have the income to support a mortgage but lacked a massive six-figure down payment has been activated. In a market where the average townhouse price now sits around $1.15M to $1.3M, this rule change is the difference between remaining in a rental or securing a permanent home.
This surge in demand is met with a supply that is still finding its "Strategic Equilibrium." While the broader Oakville market shows signs of a buyer’s market for detached homes, freehold townhomes are bucking the trend, with absorption rates jumping from 15.6% to over 21% in early 2026. This indicates that while the market is more balanced than in 2022, well-priced townhomes are moving quickly as buyers leverage new 30-year amortization options to keep monthly carrying costs manageable.
Local Nuance: Neighborhood Impact
The impact of the $1.5M rule is most visible in Oakville’s high-demand family corridors:
West Oak Trails & River Oaks: These neighborhoods are the epicenter of the townhome surge. Buyers who previously felt "capped" at a $999,000 purchase price are now aggressively bidding on listings priced at $1.2M or $1.3M, knowing they only need a fractional down payment compared to previous years.
Glen Abbey: We are seeing increased interest in older, larger townhomes that offer more square footage. These properties often land right in the $1.1M–$1.4M sweet spot, making them prime targets for the new insured mortgage rules.
Joshua Creek & The Preserve: Even in these premium enclaves, the $1.5M cap allows "entry-level" luxury seekers to secure a foothold in one of the region's top school districts without liquidating their entire investment portfolio for a down payment.
Key Market Shifts to Watch:
Lower Down Payment Hurdles: A $1.2M home that once required $240,000 down can now be secured with $95,000 (subject to insurance premiums).
Increased Competition for "Freehold" Assets: Expect more multiple-offer scenarios for townhomes under $1.5M, even as detached homes see longer days on market.
30-Year Amortization Advantage: First-time buyers are using the extended repayment period to offset 2026 interest rates, increasing their overall "buying power" by approximately 9-10%.
About the Author
Cory Martin is Broker and Co-Founder of Martin Group, serving Oakville, Burlington and the surrounding Halton communities. Martin Group has performed in the Top 1% by TRREB MLS® sales volume every year since 2008.
Partner with Oakville’s Experts
Navigating these new financial rules requires a strategy that balances speed with long-term fiscal health. Whether you are looking to capitalize on your townhome’s rising demand or seeking to break into the Oakville market using these new mortgage tools, our team provides the data-driven insight you need.
Contact Martin Group today to schedule your consultation.
Profit from our experience.
Frequently Asked Questions
How did the $1.5M insured mortgage cap change Oakville townhome buying?
It removed the 20% down payment barrier on the town’s primary townhome inventory. A property over $1M previously required a minimum $200,000 upfront; qualified first-time buyers and new-build purchasers can now enter with roughly $125,000 on a $1.5M property.
What does a $1.2M Oakville townhome require as a down payment now?
Around $95,000, subject to insurance premiums — compared with the $240,000 that the same home once required.
Are Oakville townhomes still competitive while detached homes cool?
Yes. Freehold townhome absorption jumped from 15.6% to over 21% in early 2026, bucking the broader detached slowdown. Expect more multiple-offer scenarios for townhomes under $1.5M even as detached homes see longer days on market.
Which Oakville neighbourhoods are seeing the biggest townhome impact?
West Oak Trails and River Oaks are the epicentre, with buyers who once felt capped near $999,000 now bidding on $1.2M to $1.3M listings. Glen Abbey’s older, larger townhomes land in the $1.1M to $1.4M sweet spot, and the cap even gives entry-level luxury buyers a foothold in Joshua Creek and The Preserve.